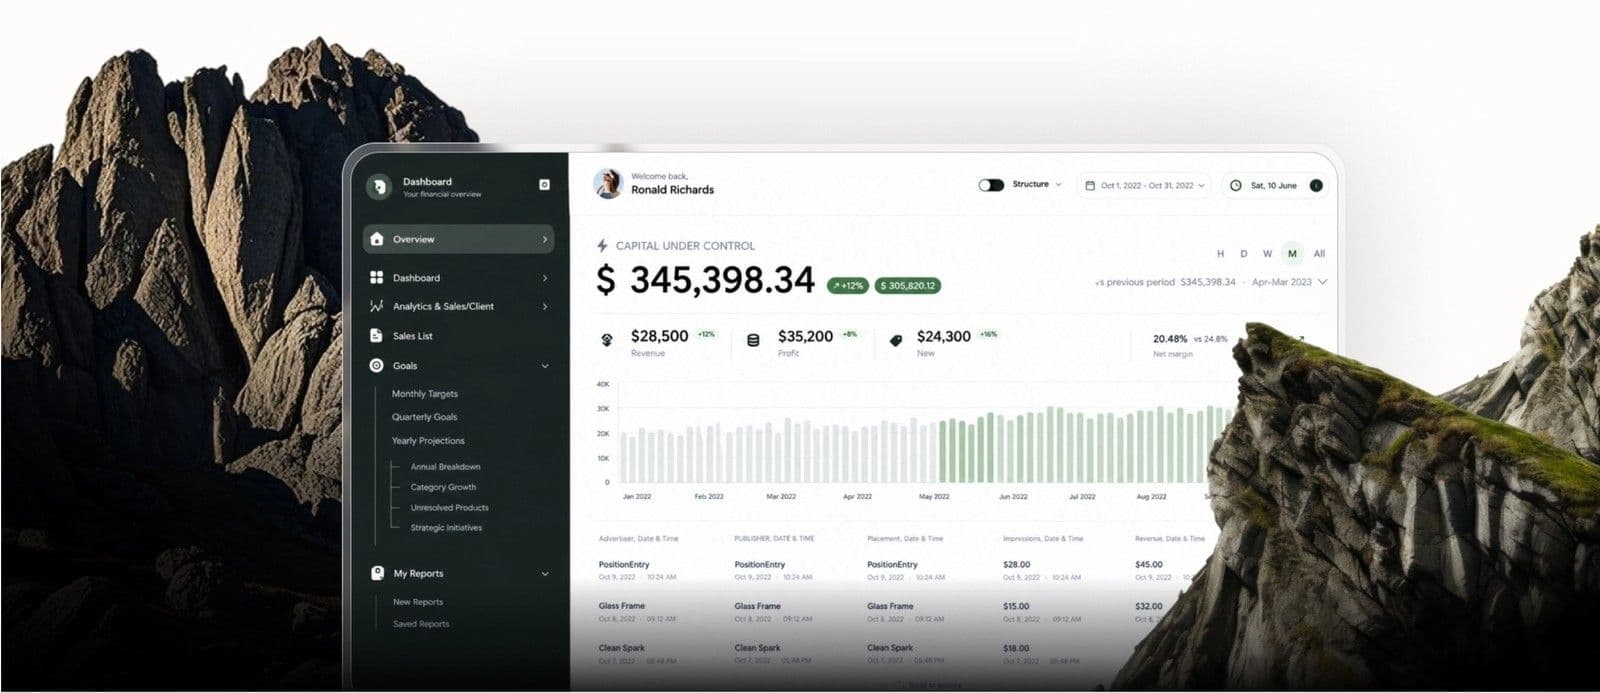
10× quarterly sales. A 0.16% chargeback ratio.
From $90K to $900K a quarter in nine months. A supplements brand scales its payment operation with PayFam, collects 97% of scheduled renewals, and brings billing and support into the growth plan.
Illustrative scenario. The merchant, figures, timeline, and founder quote are fictional, not verified PayFam customer results or forecasts.
Hypothetical outcomes
- Quarterly processed sales
- 10×
- $90K in quarter one to $900K in quarter three, across nine months.
- Third-quarter processed sales
- $900K
- The example grows from $90,000 in quarter one to $900,000 in quarter three.
- Simple chargeback ratio
- 0.16%
- 24 chargebacks against 15,000 successful charges in the example cohort.
Illustrative founder quote
“Every increase in ad spend used to mean more payment problems. We needed a plan for renewals, support, and fulfillment that could grow with us.”
Illustrative supplement subscription fulfillment. AI-generated image.
The story at a glance
Quarter 1
$90,000 in processed sales exposed renewal failures and recurring-billing questions.
Before the ramp
The team reviewed underwriting, subscription terms, billing descriptors, and support ownership.
Quarter 2
Volume rose to $450,000 through staged increases and weekly payment reviews.
Quarter 3
$900,000 was processed; 400 initially failed renewals were recovered through follow-up.
The challenge
The ads were working. Failed renewals were piling up.
The brand sold a daily supplement with a replenishment subscription. Its first quarter generated $90,000 in processed sales, and the acquisition team had found a campaign it wanted to scale. The product had repeat-purchase potential, but the payments operation was still being managed reactively.
A failed renewal could sit unresolved until a customer asked about a missing delivery. Some buyers remembered the introductory price but not the next billing date. Others did not recognize the statement descriptor and contacted their bank before contacting the brand.
The founder could see how the problems would multiply with ad spend. More subscribers meant more renewals to reconcile and more opportunities for confusing billing to become a dispute. The team needed to improve both payment execution and the experience surrounding the charge.
The brief was specific: agree on a sustainable processing ramp, recover eligible failed renewals, and give customers a clear explanation of what they had bought and how to change it.
The approach
Recover failed renewals. Clear up billing. Scale in stages.
The team began with the offer itself. It reviewed the introductory period, full renewal price, delivery cadence, cancellation instructions, and statement descriptor. Recurring terms were made visible before payment. Support took responsibility for renewal questions and reviewed complaints before the next increase in acquisition spend.
On the payment side, the brand provided its processor with the product details, claims, refund policy, and expected volume. The ramp followed the approved business profile. PayFam provided the checkout, eligible network-token vaulting, and a way to use supported processing accounts without tying the customer credential to one account.
Routing and retries served different purposes. Routing selected an eligible processing path; follow-up addressed a payment that had actually failed. The team separated failures that could be retried from cases requiring a new card or customer authentication. It did not repeatedly send every decline through multiple accounts.
Refunds, cancellations, and disputes went into a daily review using the processor’s tools and the support team’s records. Clearer terms and faster answers gave customers a direct way to resolve billing questions with the brand.
Volume increased in stages. After each step, the team checked approval rates, fulfillment delays, support demand, and refund reasons. That created a practical feedback loop: fix a billing or delivery issue before sending a larger group of customers through the same experience.
Illustrative figures
10× quarterly sales in nine months.
Processed sales across the fictional nine-month story.
The outcome
$900K processed. 97% of scheduled renewals collected.
Processed sales rose from $90,000 in quarter one to $450,000 in quarter two and $900,000 in quarter three. Across nine months, quarterly sales reached ten times the starting level.
Of 8,000 renewals due in quarter three, 7,360 succeeded on the first attempt, a 92% initial approval rate. Follow-up collected another 400, bringing the total to 7,760, or 97%. The remaining 240 stayed on the unresolved list at the cutoff.
The quarter contained 15,000 successful charges in total, including those renewal collections. At an illustrative $60 average charge, processed sales totaled $900,000. The example records 24 chargebacks for that cohort through 60 days after quarter-end: a simple ratio of 0.16%.
The founder could connect the next increase in ad spend to the team’s ability to handle it. Acquisition brought in more customers; billing, support, and fulfillment had a defined process for the extra volume. Payment reviews became part of the growth plan.
Example results
| Measure | Population or baseline | Scenario outcome |
|---|---|---|
| Quarterly processed sales | $90K → $450K | $900K in quarter 3 |
| Initial renewal approvals | 8,000 renewals due | 7,360 / 92% |
| Recovered after initial failure | 640 failed renewals | 400 collected later |
| Total collected renewals | 8,000 renewals due | 7,760 / 97% |
| Renewals still unresolved | 640 initial failures | 240 at cutoff |
| Cohort chargebacks | 15,000 successful charges | 24 / 0.16% |
How the numbers work
Quarterly sales growth is $900,000 ÷ $90,000 = 10×. Initial renewal approval is 7,360 ÷ 8,000 = 92%. Eventual collection is (7,360 + 400) ÷ 8,000 = 97%. Recovery among initial failures is 400 ÷ 640 = 62.5%; these are recovered payments, not new subscribers. The simple cohort chargeback ratio is 24 ÷ 15,000 = 0.16%, observed through 60 days after quarter-end; it is not a Visa VAMP or Mastercard monitoring calculation. Dispute handling in this scenario uses processor tools and support records, not PayFam’s upcoming Dispute Alerts feature. Processed sales are before refunds and fees and exclude tax and shipping. All inputs are hypothetical; they do not establish platform-attributable growth or guarantee network-monitoring outcomes.